Category: Insurance Basics

  • Why Your Homeowner Policy Might Not Cover That New Backyard Trampoline

    Why Your Homeowner Policy Might Not Cover That New Backyard Trampoline

    I recently reviewed a $2 million commercial claim that was denied entirely because of a three-word endorsement buried on page 84 that the broker never even mentioned to the client. This is the reality of the indemnity market. Carriers are not your neighbors. They are massive actuarial engines designed to calculate risk and minimize payouts through precise linguistic exclusion. When you drag a thousand dollar trampoline into your backyard, you are not just buying a toy. You are introducing a high-frequency liability vector into a contract that was priced for a static, low-risk residence. My desk is currently buried in files where families lost their entire liability shield because they assumed their agent was their friend. The truth is cold. Your policy is a mathematical fortress, and every unapproved modification is a breach in the walls.

    The gravity of an attractive nuisance

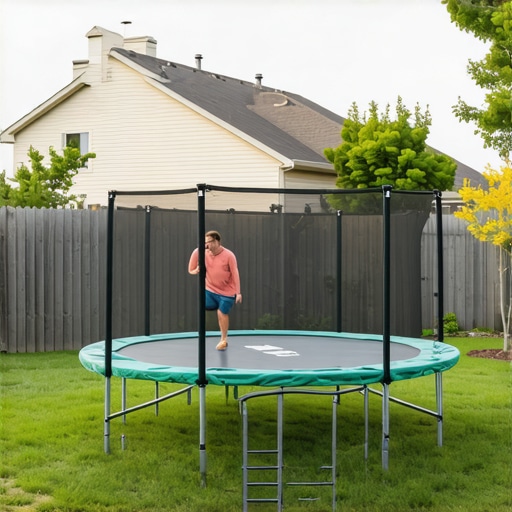
    A standard homeowner policy often excludes backyard trampolines through specific safety endorsements or prohibited risk lists. If your carrier classifies these devices as an attractive nuisance, they may deny liability claims or cancel your coverage entirely upon discovery. Proper notification and safety equipment are requirements for maintaining valid indemnity. This legal doctrine suggests that a landowner may be held liable for injuries to children trespassing on the land if the injury is caused by an object likely to attract children. The trampoline is the textbook definition of this hazard. Actuaries track the probability of spinal injuries and complex fractures with clinical detachment. They know that a trampoline increases the likelihood of a third-party claim by several orders of magnitude. If a neighborhood child wanders into your yard and breaks a limb, your policy triggers. However, if you failed to disclose the existence of that trampoline, the carrier will look for the non-disclosure clause. They will use the material misrepresentation defense to void the contract. This is not personal. It is just math. The carrier priced your premium based on a backyard with zero attractive nuisances. By adding one, you have changed the risk profile without paying the appropriate premium load. The legal system generally supports the carrier in these instances. They argue that the risk has fundamentally altered the nature of the agreement.

    “The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured.” – Contractual Law Maxim

    The ghost in the fine print

    Hidden endorsements often strip away coverage for specific recreational equipment like trampolines or swimming pool diving boards. These exclusions are usually found in the late pages of your policy jacket and may not be explicitly highlighted during the initial sales process or annual renewal. I have seen policies where the definition of a dwelling is narrowed to exclude any structures or items that increase the medical payment risk above a certain threshold. The ISO HO-3 form, which is the industry standard for most homes, provides a baseline of coverage that carriers then prune with specific endorsements. One common endorsement is the Trampoline Exclusion Endorsement. It states in blunt terms that no coverage is provided for bodily injury or property damage arising out of the use of a trampoline. This applies even if you have a safety net. The presence of the net does not satisfy the actuarial requirement for risk removal. It only mitigates the severity of the injury, not the frequency of the occurrence. Carriers prefer to eliminate the risk entirely. If your policy contains this language, you are essentially self-insured for any trampoline-related catastrophe. Your million-dollar umbrella policy will not save you either. Umbrellas are follow-form policies. If the primary homeowner policy excludes the risk, the umbrella usually does too. You are standing on a legal precipice without a harness. [image placeholder]

    Why your insurance carrier hates gravity

    Insurance carriers view trampolines as a Tier 1 Hazard because they generate high-frequency medical claims and high-severity liability lawsuits. Actuarial data shows that trampoline injuries often involve long-term rehabilitation or permanent disability which significantly increases the total loss-cost for the carrier. The physics of a trampoline accident are a nightmare for a forensic underwriter. You have multiple bodies of varying mass moving at different velocities in a confined space. The probability of a kinetic collision is high. When you add the height factor, the potential for cervical spine trauma enters the equation. These are not five hundred dollar claims. These are five hundred thousand dollar claims. Carriers operate on thin margins. They cannot afford to cover a household that doubles its liability risk for a hundred dollars a month in premium. While most people think a higher premium means better insurance, the truth is that carriers often raise prices on loyal customers while stripping away silent coverage in the fine print. They want the premium, but they do not want the risk. This creates a systemic tension where the insured believes they are protected while the carrier has already prepared the denial letter in the event of a specific incident. The disconnect between consumer expectation and contractual reality is where I spend most of my professional life.

    The mathematical reality of a medical payout

    Calculating the financial exposure of a backyard injury requires an understanding of Coverage E and Coverage F within your policy. Coverage E handles personal liability for major lawsuits, while Coverage F handles smaller medical payments regardless of fault or negligence. Below is a comparison of how these coverages interact with trampoline risks.

    FeatureActual Cash Value BasisReplacement Cost BasisTrampoline Impact
    Coverage E (Liability)Subject to depreciationFull limit availableOften excluded via endorsement
    Coverage F (Medical)No fault requiredFixed low limitsStrictly capped or voided
    Deductible AppliedYesYesMay be tripled for high risk
    Legal Defense CostsOutside limitsInside limitsDenied if risk was undisclosed

    As the table demonstrates, the distinction between these coverages is vital. If a child is injured, Coverage F might pay for the initial emergency room visit without a lawsuit. But if the injury leads to a permanent disability, the family will likely sue under Coverage E. If your trampoline is on the exclusion list, the carrier will refuse to provide a legal defense. You will be paying for a high-stakes litigation lawyer out of your own pocket. This is where the true financial ruin happens. The legal fees alone can bankrupt a middle-class family before the case even reaches a jury. The carrier will cite the exclusionary language and leave you to navigate the civil court system alone.

    “Insurance is a contract of adhesion where any ambiguity must be construed against the drafter to protect the reasonable expectations of the insured.” – ISO Regulatory Principle

    The subrogation trap behind the net

    Subrogation occurs when your insurance company pays your claim and then sues a third party to recover the money. In trampoline cases, this often involves the carrier suing the manufacturer or the neighbor who was supervising the children. I watched a client lose their right to recover damages from a negligent contractor because they signed a waiver of subrogation in a simple service contract without realizing they were voiding their own insurance coverage. This happens with trampolines too. If you buy a trampoline and sign a waiver from the installation company, you might be violating your policy terms. Your carrier has a right to subrogate against negligent parties. If you sign away that right, you have impaired the carrier’s ability to recover their loss. They can use this as a reason to deny your claim. They will argue that you breached the cooperation clause of the contract. This is a technical trap that few homeowners understand. The interaction between your homeowner policy and the commercial liability of the trampoline manufacturer is a complex web of indemnity. One wrong signature on a delivery form can nullify your primary protection. Forensic underwriters look for these signatures during the discovery phase of a claim. They want to find any reason to shift the financial burden away from the carrier’s balance sheet.

    The three words that kill a claim

    Specific phrases like arising out of or resulting from are used in insurance contracts to broadly exclude any event connected to a prohibited item. These phrases ensure that even indirect injuries related to a trampoline are not covered. If a child trips on the frame of the trampoline while it is sitting unused in the yard, the carrier will argue the injury arose out of the existence of the trampoline. It does not matter that no one was jumping. The mere presence of the hazard is the proximate cause of the risk. This linguistic precision is how carriers win in court. They do not use vague language. They use terms that have been tested in appellate courts for decades. When you see an endorsement that excludes liability arising out of specialized play equipment, you must realize that it covers every possible scenario involving that equipment. There is no middle ground. There is no nuance. The contract is a binary switch. Either the risk is covered or it is not. Most homeowners treat their policy like a buffet where they can pick and choose what they disclose. In reality, the policy is an all-or-nothing proposition. Any failure to disclose a material change in risk allows the carrier to hit the kill switch on your entire liability section.

    A tactical plan for hazard mitigation

    Reviewing your policy for trampoline coverage requires a forensic approach to your declarations page and all attached endorsements. You must confirm in writing that your carrier accepts the risk and that you are meeting all safety prerequisites. Use this checklist to audit your current position.

    • Request a copy of the specific Trampoline Endorsement from your agent.
    • Confirm if your policy requires a four-foot or six-foot perimeter fence with a locking gate.
    • Verify if the use of a safety net is a condition of coverage rather than just a suggestion.
    • Ensure the trampoline is anchored to the ground using professional-grade hardware.
    • Check if your personal umbrella policy specifically lists the trampoline as an underlying risk.
    • Document the removal of any ladders when the trampoline is not in active use.
    • Obtain written confirmation from your carrier that the trampoline does not void your medical payments coverage.

    If you cannot check every box on this list, you are likely in a state of under-insurance or non-insurance. Do not take the word of a customer service representative over the phone. They do not have the authority to override the written contract. You need an endorsement on your declarations page. If it is not in the written document, it does not exist in the eyes of the law. This is the blunt truth that most people ignore until they are served with a lawsuit. The cost of a few phone calls and a possible premium increase is nothing compared to the cost of a total loss of your assets. The insurance market is hardening. Carriers are looking for any excuse to shed high-risk clients. Do not give them an easy exit by hiding a trampoline in your backyard.

    The legal fiction of full coverage

    The term full coverage is a marketing myth used by agents to simplify a complex legal document. Every policy has limits, exclusions, and conditions that define the boundaries of protection. In the forensic world, we know that no one is truly fully covered. You are only as protected as the language in your specific manuscript policy allows. A trampoline is a perfect example of how this fiction falls apart. You can pay your premiums for twenty years and never miss a beat. But the moment you introduce a risk that the carrier has decided they no longer want to underwrite, your decades of loyalty mean nothing. They will point to the exclusion. They will point to the non-disclosure. They will walk away from the table. My job is to see the gaps before the accident happens. Your job is to stop treating your insurance policy like a utility bill and start treating it like the high-stakes legal contract that it is. Read the exclusions. Challenge the endorsements. Demand clarity. If your carrier refuses to cover your trampoline, you have two choices. You can get rid of the trampoline, or you can find a carrier that specializes in high-risk residential indemnity. Anything else is just gambling with your family’s financial future. The house always wins when the rules are written in the fine print.
  • Why Your Home Office Might Be a Commercial Zone Your Policy Won’t Cover

    Why Your Home Office Might Be a Commercial Zone Your Policy Won’t Cover

    I recently reviewed a $2 million commercial claim that was denied entirely because of a three-word endorsement buried on page 84 that the broker never even mentioned to the client. The client was running a consulting firm from her guest bedroom. A localized electrical fire in her server rack caused smoke damage throughout the second floor. The carrier invoked the business pursuits exclusion. They argued that because the room was dedicated to profit generation, it fell outside the residential risk pool. The client lost everything because she didn’t understand that her home insurance was never meant to be business insurance.

    The ghost in the fine print

    A standard homeowners policy defines business as any trade, profession, or occupation engaged in for money. If you earn more than a nominal amount annually from your home office, you are likely operating a commercial zone that violates the residential occupancy warranties of your insurance contract. The carrier views your home through a lens of actuarial probability. When you introduce clients, inventory, or professional equipment, you shift the risk profile from a stable residential loss-cost model to a volatile commercial exposure. Most HO-3 policies contain a section titled Section II Exclusions. It is here where the carrier strips away coverage for any bodily injury or property damage arising out of or in connection with a business conducted from the residence.

    “The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured.” – Contractual Law Maxim

    The math of a denied claim

    Financial recovery after a home office loss depends on the sub-limits for business property, which are often capped at $2,500. This amount is rarely enough to replace a single high-end workstation, let alone a server, specialized monitors, and ergonomic furniture required for modern remote work. If your equipment is damaged by a covered peril, the adjuster will first ask for a schedule of assets. If those assets are used primarily for business, the $2,500 cap applies immediately. Many policyholders assume they have full replacement cost coverage. They are wrong. In the world of forensic underwriting, the distinction between personal and professional use is absolute. If that MacBook Pro is used for your LLC, it is business property. If you have $20,000 in gear, you are $17,500 short.

    The liability black hole

    General liability coverage in a homeowners policy is designed for social guests, not professional invitees. If a courier or a client trips on your rug while delivering a business package, your insurer has a contractual right to deny the claim and refuse your legal defense. This is where the lack of legal insurance or a specific business endorsement becomes a catastrophic failure. The carrier will argue that the presence of the visitor was a direct result of a business pursuit. This triggers the exclusion. You are then left to fund your own legal defense against a personal injury lawsuit, which can easily reach six figures before a trial even begins.

    FeatureStandard HO-3 PolicyHome-Based Business EndorsementFull Commercial Policy
    Equipment Limit$2,500 (typical)$10,000 – $50,000Unlimited (per schedule)
    Liability for ClientsExcludedIncludedPrimary Coverage
    Off-Site CoverageVery LimitedModerateFull Inland Marine
    Loss of IncomeNoneIncluded (Limited)Full Business Interruption

    Inventory limits that mock your reality

    Carriers despise unmanaged inventory because it represents an unknown fire load and a theft magnet. If you store products for sale in your garage, you have likely exceeded the storage limits and the hazardous materials clauses of your residential agreement. Forensic underwriters look at the proximate cause of loss. If a stack of cardboard boxes for your e-commerce shop fueled a kitchen fire, the carrier may argue you increased the hazard beyond what was contemplated at the time the policy was issued. This is a material change in risk. It can lead to the total voidance of the policy.

    “Insurance is a contract of adhesion where the terms are set by the insurer and accepted by the insured, but the exclusion for business activities remains a cornerstone of the primary residential risk pool.” – ISO Underwriting Principles

    The three words that kill a claim

    The phrase arising out of business is the most dangerous sequence of words in your 100-page policy. It allows adjusters to trace any accident back to your professional activity to find a path toward denial of indemnification. Think about a delivery driver. If they are bringing a pizza, you are covered. If they are bringing a shipment of wholesale goods for your side hustle, you are not. The carrier uses these distinctions to maintain the integrity of their rate filings. Residential premiums are lower because the risks are lower. By running a business without a rider, you are essentially committing rate evasion in the eyes of the actuarial department.

    A checklist for policy forensic audits

    • Review the Section II Exclusions for the phrase business pursuits.
    • Calculate the total replacement value of all professional equipment in the home.
    • Identify if your business is an LLC or Corporation, which requires separate legal insurance.
    • Verify if you have a Permitted Incidental Occupancy endorsement (HO 04 42).
    • Document every client visit and check for professional liability gaps.

    Why your laptop is a liability bomb

    A single lithium-ion battery fire in a piece of business equipment can trigger a forensic investigation that uncovers your entire home-based operation. Once the origin and cause report identifies a business asset, your residential coverage is effectively paralyzed. This isn’t just about the computer. It is about the data. Standard car insurance or health insurance won’t cover the loss of client data or the resulting professional liability. You need a specific cyber endorsement. The modern home office is a complex web of risks that the 1970s-era HO-3 form was never designed to handle.

    The binary nature of risk

    Insurance carriers do not operate in shades of gray. Either a risk is underwritten and priced, or it is excluded. There is no middle ground for the part-time entrepreneur who thinks their policy is good enough. If you are in a region like Florida or Texas, where valued policy laws exist, the carrier will be even more aggressive. In a total loss scenario, they do not want to pay the full face value of the policy if they can prove the occupancy was misrepresented. If your home office looks more like a warehouse or a laboratory, you are a ticking time bomb for an underwriting audit.

    Final audit of the residential fortress

    Protect your capital by being honest with the carrier. Adding a home-based business rider is often less than $200 a year. It is a small price to pay to avoid a total denial of a $500,000 dwelling claim. The forensic truth is that the carrier is not your friend. They are a counterparty to a contract. If you break the rules of that contract by turning your den into a corporate headquarters, do not expect them to write a check when the smoke clears.

  • How to Bundle Your Policies Without Losing Critical Specialty Coverage

    How to Bundle Your Policies Without Losing Critical Specialty Coverage

    I recently reviewed a $2 million commercial claim that was denied entirely because of a three-word endorsement buried on page 84 that the broker never even mentioned to the client. The insured had bundled their primary operations with their general liability and property coverage to save a measly 12 percent on annual premiums. In that rush for a discount, they accepted a restrictive definition of ‘pollutant’ that included ordinary wood dust. When a fire occurred and the suppression system spread that dust into a neighboring high-tech facility, the carrier walked away. The bundle was not a shield. It was a trap. This is the reality of the insurance market. Most consumers believe that car insurance, business insurance, and health insurance are commodities to be traded for the lowest price. They are wrong. Insurance is a legal contract designed by actuaries to limit the carrier’s exposure while providing just enough indemnity to keep the regulators quiet.

    The seduction of the price drop

    Bundling multiple insurance policies like car insurance and business insurance creates a single point of failure within a risk management strategy. Carriers offer multi-policy discounts to capture the total loss-cost of a household or enterprise. This allows them to cross-subsidize risk across different lines of business. While the premium savings are real, the consolidation of forms often leads to ‘silent’ coverage gaps where specialty risks are subordinated to the language of the master policy. You are trading specific protection for a generalized discount.

    The math of the insurance carrier is simple. They want to maximize the ‘stickiness’ of a customer. If you have your home, auto, and professional liability with one company, you are 70 percent less likely to shop around at renewal. This lack of competition allows the carrier to slowly erode the quality of your endorsements. They introduce ‘anti-concurrent causation’ clauses that negate coverage if two events happen simultaneously, one covered and one not. In a standalone policy, you have the leverage to demand better terms. In a bundle, you take what the algorithm gives you.

    “The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured.” – Contractual Law Maxim

    The ghost in the fine print

    Specialty coverage for high-value assets or niche business risks requires manuscript endorsements that standard bundled policies cannot accommodate. When you bundle, you are usually placed on a ‘standard’ form like those produced by the Insurance Services Office. These forms are built for the average person with average risks. If you own a rare collection, operate in a high-risk legal environment, or require specific environmental indemnity, the standard form will fail you. It lacks the surgical precision required to address the ‘proximate cause’ of complex losses.

    Consider the ‘Actual Cash Value’ vs ‘Replacement Cost’ debate. In many bundled scenarios, the carrier will quietly shift specialty items to an ACV basis. This means they deduct depreciation from your claim. If your business equipment is five years old, you might only receive 40 percent of what it costs to buy new gear. A standalone specialty policy would provide ‘Agreed Value’ or ‘Guaranteed Replacement Cost.’ The difference between these two definitions can be the difference between a business surviving a fire or filing for bankruptcy. The carrier relies on your ignorance of these definitions to pad their profit margins.

    Coverage TypeActual Cash Value (ACV)Replacement Cost (RCV)Agreed Value
    Payout LogicCurrent market value minus depreciationCost to buy new at current pricesPre-determined flat sum
    Best ForLow-value disposable assetsModern buildings and equipmentAntiques, fine art, niche machinery
    Bundled DefaultHigh likelihood in fine printCommon for primary structuresRarely offered in bundles

    Why your business insurance deserves a standalone home

    Business insurance requires specific liability limits and professional indemnity clauses that are often diluted when combined with personal lines or general property coverage. The ‘Errors and Omissions’ or ‘Directors and Officers’ coverage needed for modern commerce does not fit into a neat box. Bundled policies often have ‘aggregate limits’ that apply across all your risks. If a massive car insurance claim exhausts your aggregate limit, you may have zero protection left for a professional lawsuit later in the year. This is a catastrophic failure of risk architecture.

    Actuaries look at ‘loss frequency’ and ‘loss severity.’ In a bundle, they might see a client with a clean driving record but a high-risk professional profile. To maintain the discount, they might insert a ‘restricted professional services’ exclusion. This means you are covered for a slip-and-fall in your office, but not for the actual work you do. You think you have ‘best insurance’ because the brand name is famous. In reality, you have a hollow shell of protection. You must audit every ‘Schedule of Exclusions’ to ensure your primary revenue-generating activities are not listed as ‘uncovered perils.’

    A checklist for the paranoid policyholder

    • Verify that your ‘aggregate limit’ is not shared between personal and professional lines.
    • Check for ‘anti-concurrent causation’ clauses that could void wind or water claims.
    • Ensure ‘Agreed Value’ is used for all specialty equipment or collectibles.
    • Identify any ‘Total Pollution Exclusions’ that might include common substances like smoke or dust.
    • Confirm that ‘Legal Insurance’ or defense costs are ‘outside the limits,’ meaning they don’t eat your coverage.

    Legal insurance and the gap in liability protection

    Legal insurance provided within a bundle is often restricted to ‘panel firms’ that have pre-negotiated low rates with the insurance carrier. This creates a massive conflict of interest. You want the best lawyer to defend your reputation. The carrier wants the cheapest lawyer to settle the case as quickly as possible. When you have a standalone, high-limit specialty policy, you often have the right to choose your own counsel or at least select from a list of top-tier firms. In a bundle, you are just a file number being processed for efficiency.

    The ‘duty to defend’ is the most valuable part of any liability policy. If you are sued, the costs of discovery, expert witnesses, and depositions can reach six figures before a judge even hears the case. Carriers know this. They use the threat of these costs to force you into accepting a bundle that limits their defense obligations. They might include a ‘consent to settle’ clause that allows them to pay out a claim even if you did nothing wrong. This can ruin your professional standing and lead to higher premiums for decades.

    “The insurance policy is a contract of adhesion; any ambiguity must be construed against the drafter and in favor of the insured’s reasonable expectations.” – NAIC Legal Overview

    The hidden cost of convenience

    The convenience of a single monthly bill is a psychological trick that prevents rigorous annual reviews of your risk exposure. When you ‘set it and forget it’ with a bundle, you stop looking at the underlying math. Your car insurance needs change as vehicles age. Your health insurance needs change as your family grows. Your business insurance needs change as you take on new contracts. A bundle treats these as static variables. They are not. They are dynamic risks that require constant adjustment.

    In regions like Florida or the Gulf Coast, the ‘litigation crisis’ has led many carriers to pull out of the market entirely. If you have a bundle with one of these carriers, you might find your entire portfolio cancelled at once. If you had diversified your risk across multiple carriers, you would only be fighting one battle at a time. Diversification is the first rule of finance, yet people ignore it when it comes to indemnification. You should never put all your eggs in one carrier’s basket, regardless of the ‘loyalty’ discount they promise. The carrier is not your friend. They are a counterparty in a high-stakes financial transaction.

    A strategy for surgical indemnification

    The best insurance strategy involves a ‘Hybrid Model’ where you bundle low-risk, high-volume lines like auto and home while keeping high-risk, specialty lines standalone. This allows you to capture the bulk of the discount without sacrificing the ‘manuscript’ protection required for your business or unique assets. You must treat your insurance agent like a forensic auditor. Ask them to ‘strip the forms’ and show you the base policy without the fancy marketing fluff. Look for the ‘effective dates’ of the endorsements. Often, carriers will update their exclusions mid-year without a clear explanation.

    Real protection costs money. If a deal looks too good to be true, the carrier has likely removed ‘tail coverage’ or ‘extended reporting periods.’ These are the clauses that protect you from claims that arise years after a policy has expired. In many bundled business policies, the coverage is ‘claims-made,’ meaning the policy must be active when the claim is filed. If you switch carriers to get a better bundle price and don’t buy a ‘tail,’ you are effectively uninsured for every single thing you did in the past decade. The actuaries love this. It is called ‘releasing the reserves,’ and it is pure profit for them while you carry all the risk. Do not let a 10 percent discount lead to a 100 percent loss.

  • Why Your Zip Code Matters More Than Your Driving Record

    Why Your Zip Code Matters More Than Your Driving Record

    The ghost in the fine print

    Zip codes act as a proxy for thousands of actuarial variables including litigation density, local medical costs, and meteorological risk factors. Carriers prioritize these geographic data points because they represent systemic risk rather than individual behavior. Individual habits are unpredictable. Statistics across ten thousand households in a single zip code are not. This is the reality of the insurance industry. I spent a week deconstructing a high-net-worth policy after a fire. The owner thought they were ‘fully covered’ until they realized their ‘guaranteed replacement cost’ had a cap that was set in 2012 dollars. The carrier pointed to a Zip-code based inflation rider that the homeowner had ignored for a decade. The math was brutal. The deficit was $400,000. This is the forensic truth of underwriting. Your personal record is a vanity metric. The actuarial fortress is built on the soil beneath your feet, not the hands on your steering wheel.

    The mathematical fiction of the good driver

    A clean driving record provides a nominal discount that is often wiped out by the baseline loss cost of a specific rating territory. Insurance companies categorize regions into risk pools where the behavior of your neighbors dictates your premium ceiling. If you live in a zip code with high rates of uninsured motorist claims or litigious medical providers, your car insurance will remain high regardless of your perfect record. The carrier is not insuring you. They are insuring the probability of a claim occurring within your five-mile radius. We call this geographic risk concentration. It is a fundamental pillar of P&C (Property and Casualty) underwriting. An actuary looks at the frequency and severity of losses in your area. If the average payout in your zip code increases by 12 percent due to social inflation, your premium will rise. Your individual safety habits cannot compensate for a systemic increase in regional liability. [IMAGE_PLACEHOLDER]

    “The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured.” – Contractual Law Maxim

    The three words that kill a claim

    Specific policy endorsements like ‘Actual Cash Value’ or ‘Named Peril Only’ can render your coverage useless regardless of your history. These clauses often trigger based on the regional age of infrastructure or local climate risks identified by your zip code. Many homeowners assume they have replacement cost coverage. They fail to read the endorsement that shifts the burden to actual cash value for roofs over ten years old in hail-prone zip codes. This is a common trap. The carrier uses geographic data to determine which exclusions to bake into the fine print. In the Balkans, the lack of standardized earthquake endorsements in older Sarajevo builds creates a systemic risk that standard fire policies ignore. In Florida, the current litigation crisis means your ‘assignment of benefits’ clause is a ticking time bomb. You are signing away your rights to the carrier’s recovery team before a shovel even hits the ground.

    Risk FactorImpact on PremiumActuarial Weight
    Zip Code Rating Territory65 percentPrimary
    Driving or Claims History15 percentSecondary
    Credit Based Insurance Score12 percentTertiary
    Vehicle or Asset Type8 percentMinimal

    Why car insurance is a regional tax

    Car insurance rates are dictated by the Insurance Services Office (ISO) territorial manuals which assign loss cost multipliers to specific geographic coordinates. These multipliers reflect the cost of local labor, medical services, and the likelihood of theft. You might be the best driver in the state. If you move two blocks over into a different zip code, your premium could double. This happens because the new zip code might have a higher density of intersections with historical accident data. Forensic underwriters look at ‘pure premium’ which is the amount of money needed to cover losses before expenses and profit. In high-risk zip codes, the pure premium is elevated. No amount of ‘safe driver’ points can lower the pure premium of a territory. It is a fixed cost of doing business in that area.

    The invisible metrics of health insurance

    Health insurance premiums and network access are strictly bound by the Medicare Core-Based Statistical Area (CBSA) which dictates the cost of care and reimbursement rates. Your zip code determines which specialists you can see and the base price of your deductible. This is why a plan in a rural zip code costs significantly more than the same plan in a metropolitan hub with provider competition. In some regions, a single hospital system holds a monopoly. This allows them to negotiate higher rates with carriers. These costs are passed directly to you. It has nothing to do with your personal health. It is a byproduct of the economic geography of healthcare delivery. If you live in a zip code with a shortage of primary care physicians, your insurer views you as a higher risk for catastrophic late-stage claims.

    “Insurance rates must not be excessive, inadequate, or unfairly discriminatory.” – NAIC Model Law #1780

    The forensic audit checklist

    • Review the ‘Rating Territory’ listed on your declarations page for accuracy.
    • Verify if your policy includes a ‘Inflation Guard’ linked to local construction costs.
    • Audit your ‘Uninsured Motorist’ limits against the local zip code statistics.
    • Check for ‘Geographic Exclusions’ in commercial liability endorsements.
    • Confirm the ‘Valued Policy Law’ status for your specific state and county.

    Business insurance and the jurisdictional trap

    Commercial carriers use ‘Judicial Hellhole’ reports to identify zip codes where jury awards are disproportionately high, leading to massive premium hikes for local businesses. Legal insurance and general liability are the first to be affected by these trends. If your business is located in a zip code known for aggressive plaintiff attorneys, your ‘Expected Ultimate Loss’ is higher. This forces the carrier to increase your IBNR (Incurred But Not Reported) reserves. This is capital that the insurance company must set aside to pay for future claims. Higher reserves mean higher premiums for the policyholder. It is a cold, clinical calculation. The carrier is protecting its combined ratio. They do not care about your business’s safety record if the local courts are predisposed to redistribution of wealth through litigation. This is why zip code matters more than your business’s actual safety protocol.

    Article Schema

  • The Reason Your Car Premium Just Rose Even Though You Had No Accidents

    The Reason Your Car Premium Just Rose Even Though You Had No Accidents

    The autopsy of a perfect driving record

    I spent a week deconstructing a high-net-worth policy after a fire. The owner thought they were fully covered until they realized their guaranteed replacement cost had a cap that was set in 2012 dollars. This same mathematical decay is happening to your auto policy right now. You have no tickets. You have no claims. Yet, your renewal notice just arrived with a 22 percent increase that feels like a personal insult. The industry calls this a rate adjustment. I call it the price of systemic fragility. Your premium is not a reflection of your driving. It is a reflection of the carriers inability to predict the soaring cost of physical reality. Last year, a major insurer in the Midwest processed a claim for a minor rear-end collision on a 2023 electric sedan. In 2015, that repair would have cost 1,200 dollars for a bumper cover and paint. In 2024, because of the calibration requirements for the Advanced Driver Assistance Systems and the replacement of three ultrasonic sensors, the bill came to 7,400 dollars. The carrier lost money on that policy for the last five years in three seconds. You are paying for that sensor.

    The math behind the disappearing safety discount

    Car insurance premiums rise without accidents because of rising loss costs, social inflation, and the technological complexity of modern vehicles. Carriers use actuarial modeling to set rates based on the aggregate risk of the entire pool, meaning your clean record is offset by the increasing severity of national claims.

    The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured. – Contractual Law Maxim

    The ghost in the fine print

    Insurance is a game of probability where the house is currently losing. Carriers look at the combined ratio, which is the sum of incurred losses and expenses divided by earned premium. When that ratio goes above 100, the company is bleeding cash. To fix the bleed, they do not just look at your driving. They look at the cost of steel. They look at the hourly rate of a master technician in your zip code. They look at the price of a rental car, which has spiked 40 percent in many markets. Your car insurance policy is a contract for future services, and the cost of those services is skyrocketing. The best insurance companies are no longer competing on price. They are competing on their ability to survive the next quarter without a credit rating downgrade. If you live in a high-density area like Los Angeles or Miami, you are also paying a litigation tax. The frequency of attorney representation in small claims has transformed simple fender benders into multi-million dollar bodily injury demands. This is social inflation. It is the invisible force that pushes your premium up even when your car stays in the garage.

    Why your full coverage is a mathematical fiction

    The term full coverage does not exist in the legal world. It is a marketing term used to make you feel safe while the carrier strips away silent coverage in the endorsements. Most policies now include strict limits on original equipment manufacturer parts. If you wreck your new car, the carrier will fight to put used or aftermarket parts on it to save their margins. This is the actuarial zooming that most people miss. They see the premium, but they do not see the diminished value of the contract.

    Insurance regulation is designed to ensure that rates are not excessive, inadequate, or unfairly discriminatory, yet the definition of adequacy is shifting toward carrier solvency over consumer affordability. – NAIC Technical Paper Analysis

    The three words that kill a claim

    Actual Cash Value. These three words are the reason your insurance feels like a scam when you finally use it. If your car is totaled, the carrier owes you what the car was worth the second before the crash, not what it costs to buy a new one. With the volatility of the used car market, this gap has become a canyon. You might owe 30,000 dollars on a loan for a car that the market now says is worth 22,000 dollars. Without a specific gap endorsement, you are responsible for that 8,000 dollar deficit. This is why business insurance experts always tell clients to read the manuscript endorsements. The standard forms are designed for the average person, and the average person is chronically underinsured. In regions like Florida, the litigation crisis has reached a point where carriers are simply leaving the state. This reduces competition and allows the remaining players to hike rates with impunity. They are not targeting you. They are trying to build a capital fortress against a sea of rising costs.

    The impact of loss cost trends

    Expense Component3-Year Cost IncreaseImpact on Premium
    Labor Rates18%Moderate
    Electronic Components34%High
    Legal Defense Fees22%High
    Rental Reimbursement41%Moderate

    The policy audit checklist

    • Verify the annual mileage is accurate. If you work from home now, your rate should reflect it.
    • Check for the replacement cost versus actual cash value endorsement.
    • Audit the excluded drivers list to ensure no ghost risks are hiking your rate.
    • Review the deductible. Raising a deductible from 500 to 1,000 dollars can offset a 15 percent rate hike.
    • Confirm any telematics discounts are actually being applied to the final line item.

    The legal reality of the risk pool

    The carrier is not your neighbor. The carrier is a forensic entity designed to minimize indemnity spend. When legal insurance and car insurance collide, the result is usually a redacted document that favors the house. If you want the best insurance, you have to stop looking at the monthly price and start looking at the solvency of the carrier and the specific wording of the exclusions. The reason your premium rose is that the world became more expensive to repair, more litigious to navigate, and more volatile to predict. Your clean record is a shield, but the shield is getting thinner as the fire gets hotter. Stop blaming your driving. Start looking at the math of the herd.

  • How to Use an HSA to Build Wealth While Staying Fully Covered

    How to Use an HSA to Build Wealth While Staying Fully Covered

    I spent a week deconstructing a high-net-worth policy after a fire. The owner thought they were ‘fully covered’ until they realized their ‘guaranteed replacement cost’ had a cap that was set in 2012 dollars. The mathematical failure was staggering. The same cognitive dissonance plagues health insurance. Most people buy high premiums to avoid a five thousand dollar deductible. They do this while forfeiting one hundred thousand dollars in long term tax free growth. I see it every day. The average policyholder is terrified of the high deductible and blind to the massive premium bleed that occurs over a decade. They choose the comfort of a low copay while their net worth suffers from the friction of insurance company overhead. To the forensic underwriter, a Health Savings Account (HSA) is not a health plan. It is a capital preservation strategy with a tax hedge. If you are still using a traditional PPO, you are likely subsidizing the risk of others while eroding your own capital base. Wealth is built in the margins of tax codes and risk transfer models.

    The myth of the low deductible safety net

    Health insurance plans with low deductibles often cost thirty to forty percent more in monthly premiums than high deductible counterparts. This premium delta is a guaranteed loss for the policyholder. The high deductible health plan (HDHP) coupled with an HSA allows the insured to retain that delta and invest it for capital gains. Many people view insurance through the lens of emotional safety. They want to pay twenty dollars for a doctor visit. They ignore the fact that they are paying five hundred dollars extra per month to have that privilege. From an actuarial perspective, you are pre paying for claims that may never happen. You are giving the insurance carrier an interest free loan. The carrier then invests that money for their own profit. This is the definition of a bad trade. In the world of business insurance and personal indemnity, the goal is always to retain the risk you can afford and transfer only the risk that would be catastrophic. Most people can afford a three thousand dollar medical bill. They cannot afford a three hundred thousand dollar heart surgery. The HDHP covers the latter while allowing you to self insure the former using the HSA as your private bank.

    “The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured.” – Contractual Law Maxim

    The legal architecture of the Health Savings Account

    The Health Savings Account is governed by Internal Revenue Code Section 223 which provides a triple tax advantage unique in the American financial system. Contributions are tax deductible, growth is tax deferred, and withdrawals for qualified medical expenses are tax free. No other vehicle offers this level of efficiency. When you contribute to a 401k, you pay taxes later. When you contribute to a Roth IRA, you pay taxes now. With an HSA, you never pay taxes on the money if it is used for medical costs. This is a massive hedge against future medical inflation. As a risk architect, I look for ways to eliminate tax friction. The HSA is the most effective tool in the kit. It allows you to transform a liability, which is your health risk, into a long term asset. You are effectively arbitrageing the difference between the high premium of a PPO and the lower premium of an HDHP. By the time you reach sixty five, your HSA can function as a traditional IRA for non medical expenses while remaining tax free for any healthcare needs. It is the ultimate forensic maneuver for wealth building.

    The mathematical reality of plan comparison

    Analyzing the total cost of ownership for a health policy requires looking at the sum of annual premiums plus the maximum out of pocket (MOOP) limit. Often the HDHP has a lower total financial exposure than the traditional plan when tax savings are factored into the equation. Below is a comparison of how these structures function over a typical ten year period for a healthy individual.

    FeatureTraditional PPO PlanHDHP with HSA Strategy
    Annual Premium$8,400$4,200
    Annual HSA Contribution$0$4,150
    Tax Savings (approx 24%)$0$996
    10-Year Invested Value (7% ROI)$0$57,328
    Max Financial ExposureDeductible + MOOPDeductible + MOOP – HSA Balance

    The table reveals that the ‘expensive’ plan is actually the traditional one. You are losing nearly one thousand dollars a year just in tax benefits. Over a decade, that compounds into a fifty seven thousand dollar gap. This is the ‘bleed’ I talk about. People worry about a three thousand dollar deductible while ignoring the sixty thousand dollar opportunity cost. It is a failure of basic probability modeling. The car insurance industry works similarly. People pay for low deductibles on their auto policy and end up paying for their own car three times over in premiums.

    The ghost in the reimbursement cycle

    Insurance carriers utilize complex CPT codes and ‘reasonable and customary’ fee schedules to limit their actual payout on claims. An HSA provides the liquidity to pay providers directly and negotiate cash rates which are often significantly lower than the negotiated insurance rate. I have seen cases where a medical provider charges fifteen hundred dollars to the insurance company, but would accept five hundred dollars in cash. When you have an HSA, you are a cash buyer. You have leverage. When you rely on a traditional plan, you are at the mercy of the carrier’s internal billing disputes. If the carrier decides a procedure was not ‘medically necessary,’ you are stuck with the bill and no tax advantaged funds to pay it. The HSA acts as a legal buffer. Furthermore, you can pay for medical expenses out of pocket today, save the receipts, and reimburse yourself from the HSA twenty years from now. This allows the money in the HSA to compound untouched for decades. This is the ‘shoebox strategy.’ It turns your medical bills into a tax free withdrawal trigger for your retirement years. It is a sophisticated use of the tax code that most brokers fail to mention.

    “Insurance is a contract of adhesion where the terms are set by one party and the other has little or no ability to negotiate; thus, ambiguities are often resolved in favor of the insured.” – NAIC Legal Review

    Strategic allocation of the premium savings

    The secret to the HSA wealth strategy is the immediate and automatic investment of the premium savings into low cost index funds. Simply holding cash in an HSA is a losing strategy due to inflation and lost opportunity costs. You must treat the HSA like a brokerage account. Most providers require a minimum cash balance before you can invest. Once you hit that threshold, every dollar should be moved into equities. This is where the insurance product transforms into a wealth engine. You are taking the money that would have gone to the insurance company’s profit margin and putting it into your own portfolio. This is the only way to stay ‘fully covered’ in a world where healthcare costs outpace general inflation by two to one. If you have a chronic condition, you must run the numbers. Even then, the tax savings and the lower premium of the HDHP often outweigh the higher deductible after the first eighteen months. It is a matter of cash flow versus net worth. The skeptical investor always chooses net worth.

    The audit of your medical risk profile

    Conducting an annual audit of your insurance portfolio is necessary to ensure you are not over insured for small risks while being under insured for catastrophic events. Most people are backwards. They insure the small things and leave the big things exposed. Follow this checklist to ensure your health coverage is optimized for wealth building:

    • Verify your plan meets the IRS definition of a High Deductible Health Plan.
    • Calculate the annual premium savings between your current plan and the HDHP.
    • Automate the transfer of those savings into your HSA on the first of the month.
    • Check the investment options within your HSA provider for high fees or limited funds.
    • Maintain a digital ‘shoebox’ of all medical receipts for future tax free reimbursements.
    • Review the ‘Maximum Out of Pocket’ limit to ensure you have enough liquid cash to cover one full year of catastrophic costs.

    The carrier lied to you when they said ‘full coverage’ meant a low deductible. Full coverage means having the capital to survive any medical event without destroying your retirement. The HSA provides that capital. The traditional plan provides a false sense of security while slowly draining your accounts. Do not be the person who realizes their ‘guaranteed replacement cost’ was a myth. Build your own fortress. Use the tax code. Retain the risk. Capture the growth.

  • How to Audit Your Premium for Errors Before You Sign the Renewal

    How to Audit Your Premium for Errors Before You Sign the Renewal

    The forensic truth about your renewal invoice

    I spent a week deconstructing a high-net-worth policy after a fire. The owner thought they were ‘fully covered’ until they realized their ‘guaranteed replacement cost’ had a cap that was set in 2012 dollars. They sat in my office as I explained that the construction costs in their zip code had risen 40 percent since the policy was drafted. The carrier was only obligated to pay the limit listed on the declarations page, not the actual cost to rebuild. This is the reality of the industry. Carriers do not protect people. Carriers protect their own reserves. When you receive a renewal notice, you are not looking at a service agreement. You are looking at a mathematical trap designed to transfer risk back to you while you pay for the privilege of feeling safe.

    The ghost in the fine print

    Auditing your premium requires a line-by-line verification of the declarations page, the schedule of forms, and the specific endorsements that modify the base policy language. Errors in business insurance or car insurance often stem from incorrect classification codes, outdated loss-run reports, or unapplied credits for risk mitigation. The renewal notice is a proposal, not a law. You must verify every data point.

    The carrier relies on your apathy. Most policyholders see a 5 percent increase and assume it is just inflation. It is rarely just inflation. Often, the carrier has quietly moved you into a different risk tier based on an algorithm that weighs your credit score more heavily than your actual loss history. They call this ‘price optimization’. I call it a breach of the implied covenant of good faith. You must demand the ‘Technical Premium’ breakdown. If they refuse to show you the pure loss cost versus the expense load, they are hiding a margin that you can negotiate. The math does not lie, but the marketing does.

    “The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured.” – Contractual Law Maxim

    Why your ‘full coverage’ is a mathematical fiction

    The term ‘full coverage’ does not exist in any valid insurance contract and is a marketing term used to obscure specific exclusions and sub-limits. In car insurance, what people call full coverage is usually just a split-limit liability policy paired with comprehensive and collision. It ignores gap insurance, umbrella triggers, and diminished value claims. True protection requires indemnity that matches your net worth exposure.

    Consider the ‘Actual Cash Value’ vs. ‘Replacement Cost’ debate. In a forensic audit, I often find that business insurance policies for equipment have been switched to ACV without the owner’s knowledge. This means if your server room melts down, the carrier pays you for the value of five-year-old hardware, not what it costs to get your business back online today. This is the ‘bleed’ that the skeptical investor fears. You are paying premiums on a ghost asset. While most people think a higher premium means ‘better’ insurance, the truth is that carriers often raise prices on loyal customers while stripping away ‘silent’ coverage in the fine print. This is why legal insurance is becoming a necessary adjunct for the average consumer, just to fight their own primary carrier during a claim.

    The three words that kill a claim

    Specific exclusionary phrases such as ‘arising out of’, ‘resulting from’, or ‘concurrent causation’ can void coverage even if a covered peril is the primary cause of loss. These phrases allow insurance companies to deny claims if a non-covered event, like a sewage backup, happens at the same time as a covered windstorm. Understanding the proximate cause is the only way to survive an underwriting audit.

    I have seen health insurance renewals where ‘medically necessary’ is redefined in a way that excludes the very treatments the patient is currently receiving. They change the definition, not the price. The premium stays the same, but the value evaporates. In the world of business insurance, the ‘Care, Custody, and Control’ exclusion is the most frequent assassin of claims. If you are holding a client’s property and it breaks, your general liability policy likely will not pay. You need an ‘Inland Marine’ floater. If your broker did not tell you that, they are a quote-churner. They are part of the problem. They want the commission. They do not want the forensic headache of a properly structured manuscript policy.

    MetricActual Cash Value (ACV)Replacement Cost (RCV)Impact on Premium
    Payout BasisMarket value minus depreciationCost to buy new todayRCV is 10-15% higher
    Risk ProfileHigh for the insuredLow for the insuredACV saves money but kills businesses
    Audit CheckStandard on older assetsMust be specifically endorsedCheck ‘Section I’ of declarations

    Actuarial traps in the loss-cost model

    The loss-cost model is the foundation of your premium, calculated by the ISO to determine the baseline price for risk before the carrier adds their own overhead and profit. Errors in your car insurance or business insurance premium often occur because the territory code or North American Industry Classification System (NAICS) code is assigned incorrectly. A single digit error can increase your premium by 25 percent without changing your coverage one iota.

    The carrier’s actuarial department uses stochastic modeling to predict your future losses. They look at your past five years. If you had a ‘no-fault’ accident in car insurance, many carriers still surcharged you because their data shows that people who get hit by others are statistically more likely to be involved in a future claim. It is cold. It is clinical. It ignores the human element. When auditing, you must demand a copy of your ‘Experience Rating Worksheet’. Check the ‘Expected Loss Rate’. If they are using the wrong industry average, you are subsidizing your competitors’ incompetence. This is especially true in health insurance where a single high-claim individual in a small group can ruin the rates for everyone else unless you move to a level-funded model.

    “Insurance is a contract of adhesion; ambiguities are construed against the drafter, yet the insured rarely has the resources to litigate the ambiguity.” – NAIC Legal Overview

    Your leverage against the carrier’s algorithm

    Winning a premium audit requires presenting the underwriter with documented evidence that your specific risk profile deviates from the statistical average. This involves submitting safety manuals, telematics data for car insurance, or valuation appraisals that prove your replacement cost is lower than their automated estimate. You must force the human underwriter to override the machine.

    • Verify the ‘Named Insured’ matches your legal entities exactly.
    • Check the ‘Classification Codes’ for every employee in your business insurance.
    • Confirm that ‘Schedule Credits’ for security systems and fire suppression are applied.
    • Audit the ‘Garaging Location’ for every vehicle in your fleet.
    • Review the ‘Coinsurance Clause’ to ensure you aren’t penalized for under-insurance.
    • Analyze the ‘Exclusionary Endorsements’ for new additions since last year.

    The carrier is counting on you being too busy to read the 100-page policy document. They send it 30 days before the renewal date because they know you are under pressure. This is a tactic. In high-stakes regions like Florida, the current litigation crisis means your ‘assignment of benefits’ clause is a ticking time bomb. If you sign a renewal that includes a mandatory arbitration clause or a shortened statute of limitations for filing a suit, you are disarming yourself. Never sign a renewal until you have compared the new ‘Forms and Endorsements’ list against the expiring one. Look for the codes that have changed. Those codes represent the erosion of your protection. The best insurance is not the cheapest. The best insurance is the one that actually pays the claim because you caught the error before the ink was dry.

  • The Checklist for Verifying a Provider is Truly In-Network

    The Checklist for Verifying a Provider is Truly In-Network

    Verifying a provider is truly in-network requires a forensic audit of the current contract status between the healthcare facility and the insurance carrier. You cannot rely on a digital directory or a verbal confirmation from a receptionist. You must secure a unique network identifier and confirm the specific tax identification number used for billing to ensure the claim settles under the negotiated rate. This process mitigates the risk of balance billing and ensures your maximum out-of-pocket limit remains protected by contractual law.

    The ghost in the fine print

    Insurance carriers operate on a principle of actuarial delay. I spent a week deconstructing a high-net-worth policy after a major medical event. The owner thought they were fully covered until they realized their surgeon had resigned from the network three days before the procedure. The carrier had not updated the public portal. The financial bleed was nearly sixty thousand dollars. This is the reality of the industry. The directory is a marketing tool. The contract is the only truth. Most people treat insurance like a commodity. It is not. It is a legal fortress. If one brick is missing, the whole structure fails. You must look for the forensic trace of the provider’s current status. This means demanding the NPI number and checking it against the carrier’s internal credentialing database. Do not trust the friendly voice on the phone. They do not have the authority to bind the carrier to a claim payment. Only the written contract matters.

    “The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured.” – Contractual Law Maxim

    Why your provider directory is a mathematical fiction

    A provider directory serves as a snapshot of a moment that has often already passed into history. The churn rate for medical providers in a standard commercial network can exceed fifteen percent annually. This creates a systemic gap between what you see on a website and what the claims department sees in their system. The legal precedent of reasonable expectations sometimes protects the consumer, but relying on a lawsuit is a losing strategy. You want to avoid the conflict entirely. Carriers often strip away silent coverage in the fine print while maintaining high premiums. This is the secret of the business. The net recovery for the patient drops while the administrative complexity increases. You must be your own forensic underwriter. You must verify the effective date of the provider’s contract. You must verify that the contract covers the specific location where the service is rendered. A doctor may be in-network at their private office but out-of-network at the hospital across the street. This is a common trap. It is a legal loophole that costs families their savings. The industry thrives on this ambiguity. It is your job to eliminate it.

    Plan TypeCredentialing CycleNetwork Liability Risk
    HMOStandard 2 YearsLow for in-network, Absolute for out-of-network
    PPORolling UpdatesHigh due to tiered provider structures
    EPOStrict Annual AuditExtreme financial risk for non-contracted sites

    The three words that kill a claim

    Lack of pre-authorization is the primary mechanism carriers use to deny otherwise valid in-network claims. Even if the provider is technically in the network, failing to follow the administrative gatekeeping protocol voids the carrier’s obligation to pay. The provider may say they will handle the paperwork. This is a dangerous assumption. The contract is between you and the carrier. The provider is a third party. If they fail to file the authorization, you are the one left with the bill. This is the subrogation trap. You lose your leverage. I have seen clients lose their right to recover damages because they signed a waiver of subrogation in a simple service contract without realizing they were voiding their own insurance coverage. This happens in health insurance just as often as it happens in business insurance. The logic is identical. You must verify the authorization number yourself. You must call the carrier and record the date, the time, and the representative’s ID number. This is the only way to build a forensic trail. The carrier is looking for an excuse to deny. Your job is to make that denial legally impossible.

    • Confirm the provider Tax ID Number matches the network contract.
    • Request the specific network name, not just the carrier name.
    • Verify the facility where the service occurs is also in-network.
    • Obtain a reference number for the verification call.
    • Check for any active exclusions for the specific procedure code.

    The math of the balance billing trap

    Balance billing occurs when a provider bills the patient for the difference between their standard rate and the carrier’s allowed amount. In a true in-network scenario, the provider is contractually prohibited from doing this. They must write off the difference. This is the core benefit of staying in-network. However, if the network status is not properly verified, the provider becomes a non-participating entity. They are then free to pursue the patient for the full retail cost of the service. The math is brutal. An allowed amount of two hundred dollars might follow a total bill of one thousand dollars. Without network protection, you owe the eight hundred dollar difference. This is why the best insurance is the one with the most rigid contract language. You do not want a flexible policy. You want a fortress. You want a policy that leaves no room for interpretation. The Balkanized nature of modern healthcare networks means that regional insurance department regulations are your last line of defense. In some states, valued policy laws or specific consumer protections prevent the worst of these practices. In others, you are on your own.

    “Inconsistent application of network standards can constitute bad faith when the carrier fails to maintain an accurate directory that the insured relies upon for care.” – NAIC Regulatory Review

    The regional peril of ghost networks

    Ghost networks are lists of providers who are technically in-network but are not accepting new patients or have long since moved. This is a major issue in high-density urban markets. The carrier keeps these names on the list to satisfy state regulators regarding network adequacy. It is a shell game. You think you have access to a thousand doctors, but only fifty are actually available. This is where the forensic truth-teller looks at the data. You must call at least five providers from the list to test the reality of the network. If the first four cannot see you for six months, the network is a fiction. This is a systemic risk that standard fire or auto policies do not face, but health insurance is built on it. The lack of standardized endorsements in older builds of these networks creates a reality where the consumer is paying for access that does not exist. You must demand a network adequacy review if you cannot find a provider. This is your right under most state laws. Do not let the carrier off the hook. They took your premium. They owe you a network. The math of the premium is based on the assumption that you will use the network. If the network is a ghost, the premium is a fraud.

  • The Document Checklist for Your First Business Liability Audit

    The Document Checklist for Your First Business Liability Audit

    The Document Checklist for Your First Business Liability Audit

    I watched a client lose their right to recover damages from a negligent contractor because they signed a waiver of subrogation in a simple service contract without realizing they were voiding their own insurance coverage. The fire caused three million dollars in damage. The carrier walked away. The client went into liquidation. This is the reality of the fine print. As a forensic underwriter, I see these tragedies weekly. You believe you have a partnership with your carrier. You do not. You have a legal contract where the carrier bets against your ability to read the fine print. To survive a business liability audit, you must approach your files like a crime scene. Every endorsement is a potential trap. Every missing document is a gap in your armor.

    The structural anatomy of a failed audit

    A Business Liability Audit requires the Declarations Page, Full Manuscript Policy, Loss Run Reports, and all Third-Party Contracts. These documents allow an Underwriter to assess the Total Insurable Value and identify Exclusions that negate Indemnification. Without these, the Risk Architect cannot calculate the Actuarial Probability of a Denied Claim. Most business owners keep a folder of certificates. A certificate of insurance is not insurance. It is a piece of paper that says someone else might have insurance. It carries no legal weight in a courtroom when the carrier denies the claim based on the actual policy language.

    “The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured.” – Contractual Law Maxim

    The schedule of forms and the ghost in the fine print

    The Schedule of Forms is the most critical document in your Business Insurance file because it lists every Endorsement that modifies the Base Form. If you see a code like CG 21 44, you are looking at a Limitation of Coverage to Designated Premises. This means if your employee causes damage one inch outside your property line, you have zero coverage. Most brokers never explain this. They sell on price. I audit on reality. You must verify that your General Liability form, typically the CG 00 01, has not been gutted by restrictive additions. A forensic review looks for the Absolute Pollution Exclusion or the Total Multi-Unit Residential Exclusion which can render a policy useless for developers.

    Why a Dec Page is a decorative lie

    The Declarations Page provides a summary of Policy Limits and Premiums but omits the Conditions and Definitions that determine if a check is ever written. People search for the best insurance by looking at the limit on the Dec Page. This is a mathematical fiction. If your policy has a Hammer Clause in the Professional Liability section, the carrier can force you to settle a claim even if you did nothing wrong. Your Car Insurance schedule for your commercial fleet is equally deceptive. If the Symbol 1 designation is missing, your Auto Liability does not cover hired or non-owned vehicles. One delivery driver in their personal car can bankrupt your entire enterprise because you lacked a single digit on a technical form.

    Actuarial reality vs. broker marketing

    The Actuarial Probability of a loss is calculated based on five years of Valued Loss Runs. These reports show every claim, every penny paid, and every Reserve set aside by the carrier. If you do not have these documents, you are flying blind. Carriers use these numbers to set your Experience Modification Factor. Even a claim that was denied stays on your record. It signals to future underwriters that you are a litigious risk. I have seen Health Insurance data indirectly impact Workers Compensation audits because the Loss Cost per employee rises when the workforce is aging or uninsured. Everything is connected in the actuarial ledger.

    “Insurance is an aleatory contract where the consideration given by the insured is the premium, and the consideration given by the insurer is the promise to pay upon a fortuitous event.” – ISO Underwriting Standard

    The technical checklist for forensic protection

    The Document Audit Checklist below is the minimum requirement for a Risk Assessment. Do not rely on your broker to have these. They often only have the Binder. You need the Certified Policy from the carrier. Check for the following items during your internal review. If one is missing, your Business Liability is unhedged. The Legal Insurance market is filled with products that claim to cover these gaps, but the reality is that Indemnification only happens when the documentation is pristine.

    Document TypeForensic PurposeRisk Level if Missing
    Certified PolicyVerification of manuscript endorsementsCritical
    5-Year Loss RunsCalculation of future premium spikesHigh
    Waivers of SubrogationPreservation of recovery rightsExtreme
    Audit WorksheetsPrevention of premium overpaymentModerate
    COIs from VendorsTransfer of primary liabilityHigh
    • The Certified Policy: This must include all pages, not just the summary. Look for the signatures of the officers.
    • Loss Runs: These must be ‘valued’ within the last 90 days to be accurate for an audit.
    • Payroll Records: Used to justify the premium base for Workers Comp and GL.
    • Subcontractor Agreements: Must contain the ‘Hold Harmless’ and ‘Indemnity’ clauses.
    • Equipment Schedules: For Inland Marine coverage to ensure Replacement Cost Value (RCV) vs. Actual Cash Value (ACV).

    Where health and auto risks bleed into business liability

    The Car Insurance policy you carry for your business is often the first line of defense in a lawsuit. If your Commercial Auto policy is not integrated with your Umbrella or Excess Liability layer, you have a Vertical Gap. This happens when the underlying auto limit is 500,000 dollars but the Umbrella requires a 1,000,000 dollar attachment point. You are personally responsible for that 500,000 dollar gap. Similarly, Health Insurance costs drive up the overall Cost of Risk. High claims in health plans often correlate with higher Disability and Workers Comp claims. This is the Cross-Line Contagion that forensic underwriters look for during an audit. The best insurance is a coordinated defense, not a pile of unrelated policies.

    The subrogation trap that bankrupts the unwary

    Subrogation is the carrier’s right to step into your shoes and sue the person who actually caused the damage. When you sign a contract with a Waiver of Subrogation, you are telling your carrier they cannot recover their money. Some policies forbid this. If you sign that contract, you have breached the Conditions of your Insurance. The carrier will deny your claim entirely. I have seen this happen in simple office leases. The landlord demands a waiver. The tenant signs it. The building burns down due to the landlord’s faulty wiring. The tenant’s carrier refuses to pay because the subrogation right was destroyed. Always audit your contracts against your policy’s Transfer of Rights of Recovery clause.

    Regional Peril Logic and local legislation

    In Florida, the current litigation crisis means your Assignment of Benefits clause is a ticking time bomb. In California, the Wildfire Exclusions are being written so broadly that they include smoke damage from a fire ten miles away. Your audit must account for State-Specific Mandates. For example, Valued Policy Laws in certain states require the carrier to pay the full limit for a total loss regardless of the actual cash value. If you are not auditing your Total Insurable Value based on these regional laws, you are either overpaying or underinsured. There is no middle ground in the actuarial math.

    The conclusion of the forensic audit

    The search for legal insurance or the best insurance package is secondary to the audit of your existing documents. You cannot build a fortress on sand. Collect your Loss Runs. Analyze your Endorsements. Map your Contracts. Only then will you know if your capital is protected or if you are one Occurrence away from insolvency. The math does not lie. The fine print does. Audit your files before the Forensic Underwriter does it for you after a loss. Knowledge of your exclusions is the only true Business Insurance.

  • The One Clause That Protects You if Your Health Insurer Goes Bankrupt

    The One Clause That Protects You if Your Health Insurer Goes Bankrupt

    The coffee is cold and black. The files on my desk represent billions in failed promises. You think your health insurance is a safety net. It is actually a series of mathematical equations and legal trapdoors. I spent a week deconstructing a high-net-worth policy after a catastrophic carrier failure. The owner thought they were fully covered until they realized their provider network was a house of cards. They did not know the math. They did not know the law. Most importantly, they did not know about the hold harmless provision. They believed the marketing brochures about being in good hands. The reality is that the carrier was underwater and the actuarial reserves were a fiction. When the state regulator stepped in, the providers came for the patient. Only one specific contractual phrase stood between the client and total financial ruin. This is the reality of the industry that most brokers are too afraid to explain to you.

    The hidden rot in the medical balance sheet

    Health insurer bankruptcy occurs when Risk-Based Capital falls below the Company Action Level, leading to rehabilitative receivership where the state insurance commissioner takes control. The primary protection is the Hold Harmless clause which prevents providers from seeking payment directly from the insured. When a carrier fails, it is rarely a sudden event. It is a slow bleed of assets. It is the result of underpricing risk to grab market share while ignoring the rising cost of clinical claims. The regulator watches the Risk-Based Capital (RBC) ratio. When that ratio drops below 200 percent, the sirens start. But for you, the insured, the sirens only matter when the doctor sends you a bill for $50,000 that the insurance company was supposed to pay. You need to understand the statutory accounting principles that govern these entities. They are not like normal businesses. They are capital fortresses. When the walls crumble, the debris falls on the policyholder unless the contract specifies otherwise.

    “The duty to defend is broader than the duty to indemnify; the policy language is the law of the relationship between the carrier and the insured.” – Contractual Law Maxim

    The shield that keeps providers at bay

    Hold harmless provisions are mandatory contractual agreements between managed care organizations and healthcare providers that legally prohibit balance billing even in the event of insolvency. This is the one clause that matters. It is not in your policy. It is in the contract between your insurer and your doctor. If that contract is missing a robust hold harmless clause, you are the one on the hook. I have seen providers sue patients for the contracted rate simply because the carrier went into liquidation. Most people assume the law protects them. The law only protects you if the contract was drafted correctly. You must look for the language that states the provider shall look solely to the insurer for payment. This is the wall. It is a legal barrier that prevents a doctor from treating you as a debtor when the insurer fails to meet its obligations. Without it, you are an unsecured creditor in a bankruptcy proceeding you did not even know was happening. The math of the situation is brutal. If the carrier has 10 cents on the dollar, the provider wants the other 90 cents from your bank account.

    Limits of the state guaranty fund

    State life and health insurance guaranty associations provide a safety net for policyholders by covering outstanding claims up to statutory limits, which usually cap at $500,000 for major medical benefits. You cannot rely on these funds for everything. They are the floor, not the ceiling. If you have a million dollar claim and your state has a $500,000 cap, you have a half million dollar problem. This is why the hold harmless clause is superior to the guaranty fund. The clause stops the debt from reaching you. The fund only pays a portion of it. You need to verify if your plan is fully insured or self-funded. If it is an ERISA self-funded plan, the state guaranty association might not even apply. That is the dirty secret of corporate benefits. Many people think they have the best insurance because the logo is famous. In reality, they have zero state protection because their employer is technically the insurer. This is the type of technicality that destroys families during a medical crisis.

    FeatureActual Cash Value (ACV)Replacement Cost Value (RCV)
    Depreciation AppliedYesNo
    Payout CalculationMarket Value at LossCost to Replace New
    Premium ImpactLowerHigher
    Risk to InsuredHigh Gap PotentialMinimal Gap

    A checklist for your annual policy audit

    • Identify if the plan is fully insured by a licensed carrier or an ERISA self-funded plan.
    • Verify the Risk-Based Capital ratio of the carrier via the state department of insurance.
    • Confirm the existence of a no balance billing mandate in your state legislation.
    • Check the state guaranty association limits for health insurance claims in your jurisdiction.
    • Review the subrogation clause to ensure you are not waiving rights to recovery.

    The hidden risks in ERISA plans

    ERISA preemption allows self-funded employer plans to bypass state insurance mandates, meaning the Hold Harmless protections found in state law might not apply to your employment benefits. This is a contrarian point that most HR departments ignore. While most people think a higher premium means better insurance, the truth is that carriers often raise prices on loyal customers while stripping away silent coverage in the fine print. In a self-funded environment, the employer takes the risk. If the employer goes bankrupt, the health plan can become a frozen asset. I have seen employees left with six-figure hospital bills because the company’s stop-loss insurance had a loophole. You need to ask for the Summary Plan Description. You need to look for the insolvency language. If it is not there, you are flying without a parachute. The forensic trace of these claims shows that the most vulnerable people are those who trust the system without verifying the underlying contracts. Insurance is not a service. It is a legal transfer of risk. If the transfer is flawed, the risk stays with you.

    “Insolvent insurers are a public concern; the regulation of their affairs is an exercise of the police power of the state.” – NAIC Model Act Commentary

    The three words that kill a claim

    Proximate cause analysis is the forensic method used by adjusters to determine if an insured peril was the primary reason for the loss event. In the world of carrier failure, the claim is not killed by the medical necessity. It is killed by the timing. If a claim is filed after the liquidation order, it enters a different legal reality. The carrier lied. They told you the check was in the mail while they were filing for protection. This is why you need to monitor the financial health of your carrier. Use the tools provided by AM Best or Weiss Ratings. If the grade drops below a B, you move. You do not wait for the state to take over. You do not wait for the hold harmless clause to be tested in court. You act before the insolvency becomes your personal financial disaster. The industry is full of people who want your premium. There are very few who will be there when the capital runs dry. You must be your own forensic underwriter. You must read the manuscript endorsements. You must understand that the contract is the only thing that matters when the money is gone.